Shell is selling billions of dollars of assets while simultaneously making one of its biggest recent acquisitions — a striking illustration of how Chief Executive Wael Sawan is reshaping the energy giant.
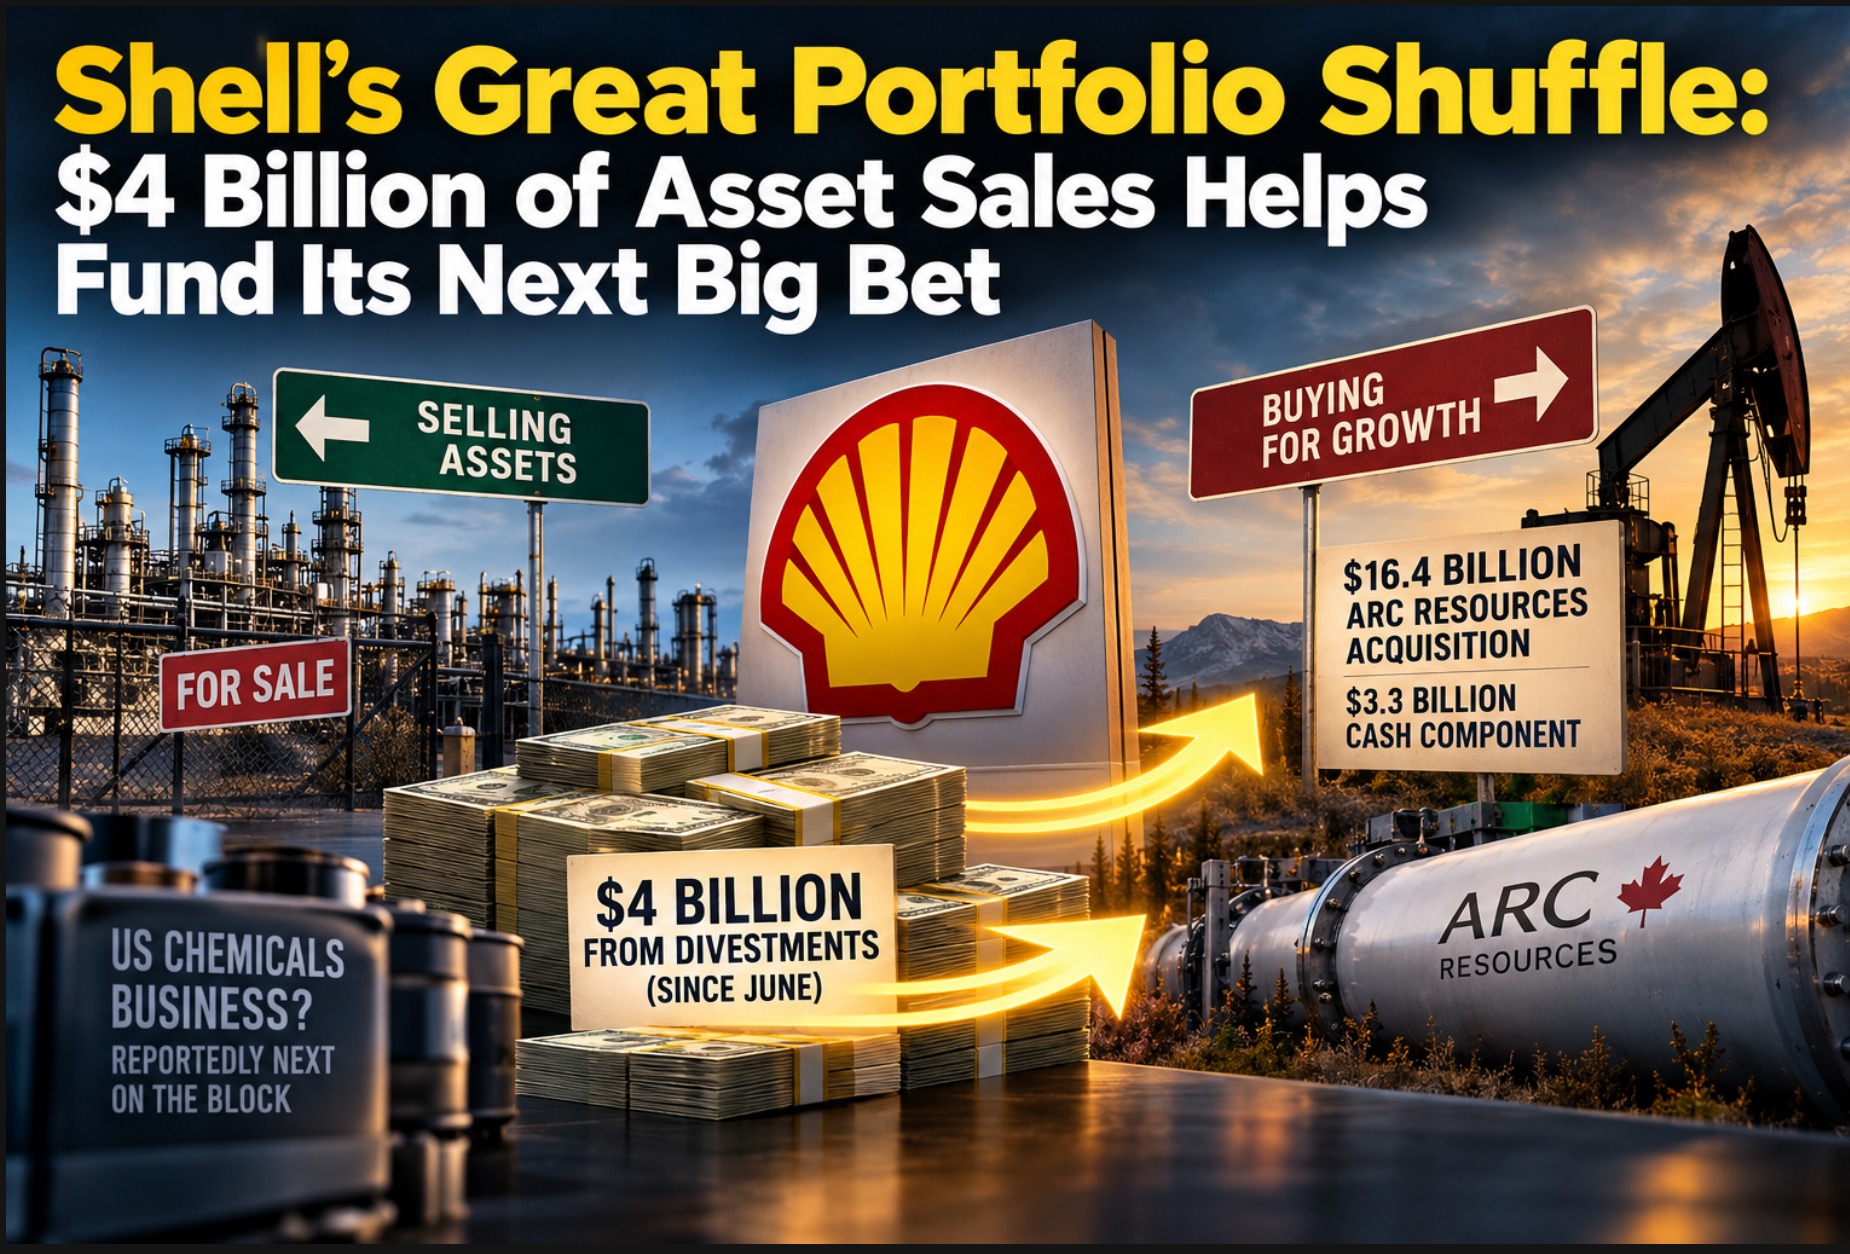
A new Energy Intelligence analysis reports that Shell has raised around $4 billion from divestments since June, helping provide financial firepower following its acquisition of Canadian producer ARC Resources and supporting the company’s continuing emphasis on shareholder returns.
The interesting story is not any single disposal.
It is the scale of the portfolio reshuffle taking place behind the familiar Shell emblem.
Sell here, buy there
Shell completed its acquisition of ARC Resources on 2 September 2026.
The final numbers are substantial.
Shell valued the acquired business at approximately $16.5 billion including net debt and leases. ARC shareholders received an equity package worth approximately $13.9 billion, funded through $3.3 billion in cash and $10.6 billion in newly issued Shell shares.
In return, Shell acquired a major position in Canada’s Montney basin.
ARC adds approximately 370,000 barrels of oil equivalent per day of liquids and gas production. Shell says the acquisition should help increase its production compound annual growth rate to around 4% through 2030 compared with 2025.
Shell CEO Wael Sawan describes ARC as a source of long-duration, low-cost liquids production and says the combination should unlock value through integration.
Shell expects the acquisition to generate double-digit returns and become accretive to free cash flow per share from 2027.
Those are Shell’s expectations. Whether the acquisition ultimately delivers those returns will only become clear over time.
Meanwhile, the disposal machine keeps running
Shell has hardly been standing still on the other side of the ledger.
One prominent example was the disposal of Jiffy Lube International and Premium Velocity Auto to an affiliate of Monomoy Capital Partners for $1.3 billion, completed on 1 July. Shell retained its Pennzoil, Quaker State, Rotella and other lubricants brands in the United States and Canada.
Then, on 30 June, Shell announced an agreement to sell its 50% non-operated interest in the Na Kika platform and associated fields, together with its Coulomb tieback interests in the Gulf of America, for total consideration of $1.7 billion, subject to adjustments and contingent payments.
These are not trivial housekeeping exercises.
Billions of dollars are moving out of one collection of Shell assets while billions are being committed elsewhere.
What could be next?
The Energy Intelligence report raises an especially interesting possibility: further rationalisation of Shell’s enormous chemicals portfolio.
This is not entirely unexpected.
Shell has previously been reported to be examining options for chemicals assets in the United States and Europe as part of the wider effort to concentrate capital in businesses offering stronger returns.
Any potential transaction should, of course, be distinguished from an actual announced sale. Until Shell identifies assets, a purchaser and agreed terms, speculation about what might ultimately be disposed of remains just that.
But the direction of travel is worth watching.
Chemicals was once an almost automatic component of the traditional integrated international oil-company model.
Under today’s Shell, historical attachment appears to carry considerably less weight than prospective returns.
The shareholder-return equation
There is another important dimension to all these disposals.
Shell has made shareholder distributions a central element of its financial proposition.
Money generated by selling assets gives management greater flexibility to fund acquisitions, capital expenditure, debt reduction, dividends and share repurchases.
That does not mean that a dollar received from an asset disposal can simply be described as a dollar subsequently spent on a buyback or acquisition. Shell’s finances do not operate as separate labelled pots of money.
But divestments unquestionably contribute to the overall pool of capital available to management.
The Energy Intelligence analysis therefore provides a useful way of looking at Shell’s recent activity: the company is not merely disposing of unwanted assets.
It is recycling capital on a very large scale.
A constantly changing Shell
There is a broader historical point here.
Anyone who has followed Shell for decades knows that the collection of businesses sitting beneath the Shell name is far from permanent.
Coal disappeared.
Large portions of chemicals have changed hands.
Refineries have been sold.
Retail operations have been bought, sold and reorganised.
Renewable-energy and power businesses have been acquired, expanded, restructured or disposed of.
Oil and gas interests are continuously purchased and sold.
And now Shell has spent approximately $16.5 billion, including assumed debt and leases, adding ARC Resources and its enormous Canadian resource base.
ARC itself says the transaction gives Shell a further 1.5 million-plus net acres in the Montney, complementing Shell’s existing approximately 440,000 net acres there. When the transaction was announced, the companies said ARC brought roughly 2 billion barrels of oil equivalent of proved plus probable reserves.
That also links directly to another pillar of Shell’s strategy: LNG.
Shell’s existing Groundbirch operations supply gas to LNG Canada, in which Shell holds a 40% interest. Shell specifically identified ARC’s gas reserves as having the potential to support future LNG growth in Canada.
So behind what might initially look like a collection of unrelated transactions is a discernible strategy.
Sell assets that management believes no longer deserve the capital.
Concentrate investment elsewhere.
Strengthen gas and LNG.
Maintain substantial oil production.
And keep returning cash to shareholders.
The $16.5 billion question
The ultimate test is not how much money Shell can raise by selling businesses.
A corporation the size of Shell can plainly generate impressive disposal figures.
The more important question for shareholders is whether management is selling the right assets — and whether the assets being acquired with Shell’s capital ultimately generate superior long-term returns.
ARC Resources will provide an unusually large test of that proposition.
Shell says the transaction will produce double-digit returns and increase free cash flow per share from 2027. Those are measurable claims against which the acquisition can eventually be judged.
And if Shell proceeds with substantial further chemicals disposals, another major piece of the old integrated Shell portfolio could be heading for the exit.
The famous red-and-yellow Shell emblem may remain reassuringly familiar.
What sits behind it is changing remarkably quickly.
Sources: Energy Intelligence, Shell’s Ongoing Divestments Help Pay for Arc, Boost Returns, 25 September 2026; Shell plc announcements concerning the ARC Resources acquisition, Jiffy Lube/Premium Velocity Auto disposal and US upstream portfolio.