From Swiss trademarks and Bahamas trading profits to Dutch tax secrecy, Shell’s financial history has acquired an impressive recurring theme: when the numbers become interesting, the explanation becomes complicated. Very complicated.
SATIRE — based on documented events, published investigations and official regulatory records.
After three Shell tax articles in a single morning, readers might reasonably wonder whether we are in danger of becoming repetitive.
Not at all.
Shell has thoughtfully provided several decades of material.
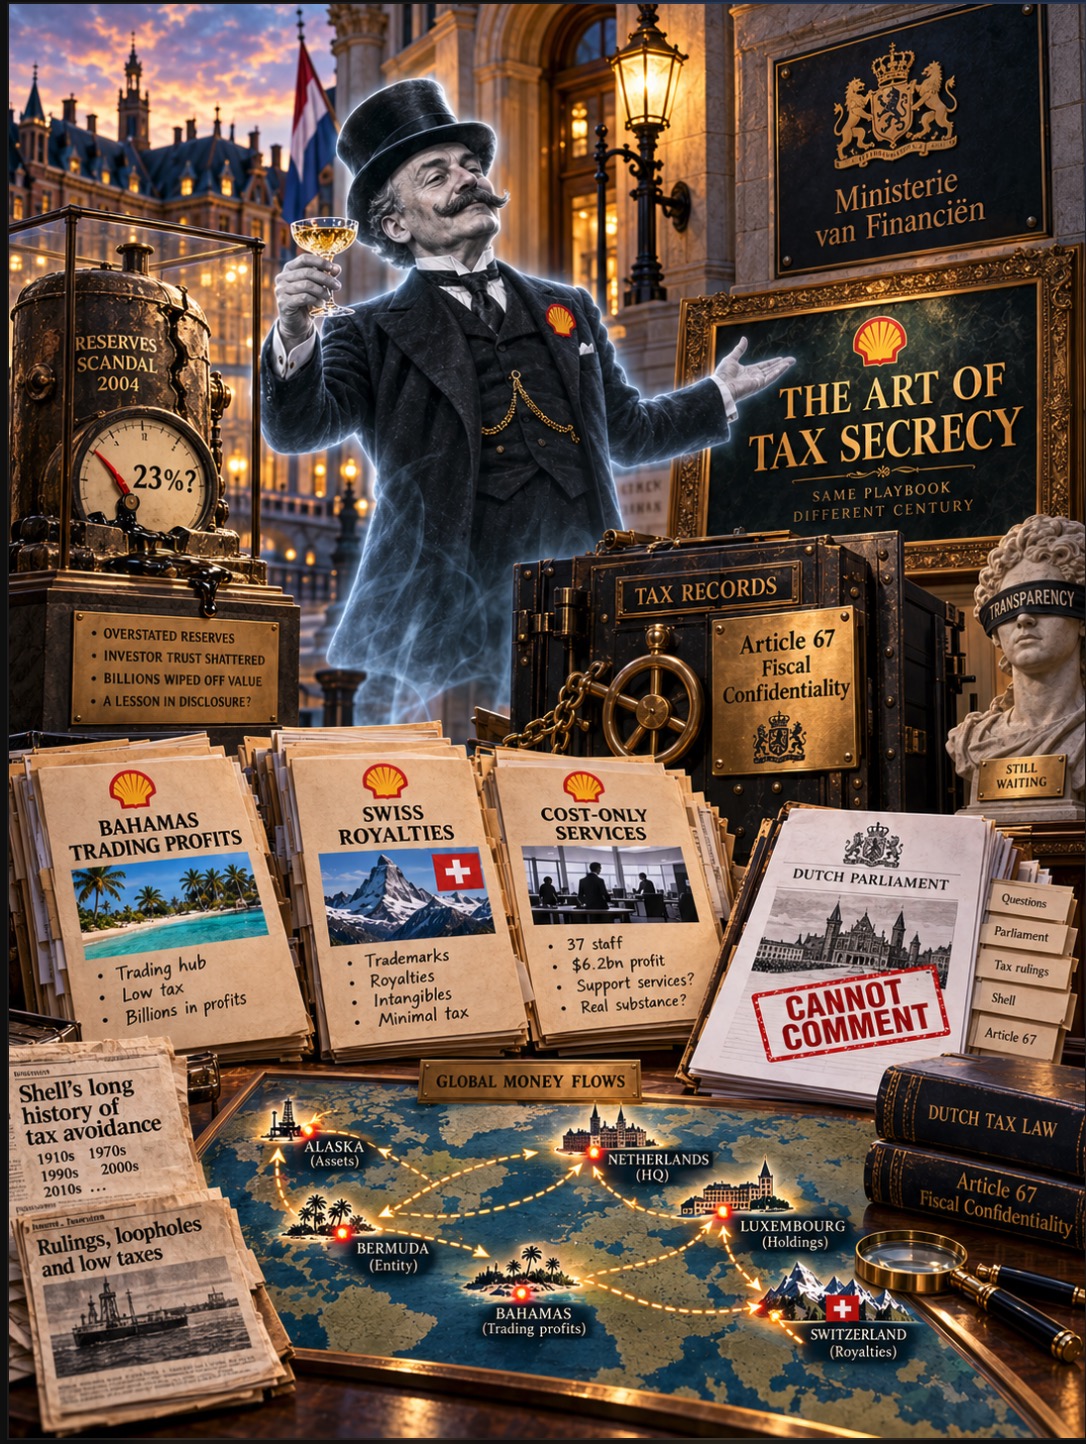
Today we learned that the Dutch Ministry of Finance cannot discuss Shell’s leaked transfer-pricing arrangements because they remain protected by fiscal confidentiality — despite the relevant documents having been leaked, published, analysed by researchers, debated by tax academics, defended by Shell and placed before Parliament.
Earlier, our deceased guest columnist Sir Henri Deterding expressed admiration for this achievement.
Everything is public.
Everyone can read it.
But the people who know whether the tax authority agreed with it are forbidden from saying so.
Even Deterding could hardly have designed a better system.
And he was very good at systems.
Shell tax avoidance: apparently not a new hobby
Readers encountering the 2026 Shell Files controversy for the first time might assume that offshore structures, Swiss intellectual property, low-tax jurisdictions and inventive intra-group arrangements represent some exciting new innovation.
Our archive rather spoils that theory.
The Royal Dutch Shell Tax Avoidance Index, assembled years ago, preserves reporting stretching back through earlier controversies involving Switzerland, Bermuda, Luxembourg, Australia, Alaska and the United Kingdom.
Among the contemporary reports indexed there were:
The Guardian, 2009: Shell had transferred ownership of its famous trademarks to Switzerland.
Dutch reporting, 2013: Shell and ABN Amro were described by critics as “masters in tax avoidance.”
US reporting, 2013–14: Shell’s handling of the Kulluk Arctic drilling rig became embroiled in allegations that tax considerations influenced its movements.
Australian reporting, 2015: scrutiny of Shell’s tax position included substantial intercompany financing costs paid to offshore Shell entities.
The old index is still available here. Royal Dutch Shell Tax Avoidance Index
The terminology has evolved.
So have the jurisdictions.
But the general subject matter has a reassuring familiarity.
The Shell logo went skiing in Switzerland
One particularly useful historical reference comes from The Guardian’s 2009 Tax Gap investigation.
The newspaper reported that legal ownership of Shell’s globally recognised trademarks had been transferred to Shell Brands International AG in Switzerland.
That Swiss entity could then receive royalties from other Shell companies using the trademarks.
Shell told the Guardian that the move was undertaken for “entirely commercial” reasons, enabling more effective and consistent management of its trademarks.
Which is perfectly possible.
Switzerland is, after all, famous for mountains, watches, chocolate and unexpectedly efficient management of multinational intellectual property.
The Guardian also reported that Shell’s corporate restructuring following the 2005 unification had placed the parent company’s tax residence in the Netherlands. The Guardian
Fast-forward seventeen years and the newly leaked Shell Files are once again examining Swiss Shell royalties.
One could almost believe in corporate tradition.
Bahamas: population 400,000, Shell traders 37, profits $6.2 billion
Then we reach the Bahamas.
According to SOMO’s 2026 analysis, Shell Western Supply and Trading Limited recorded approximately $6.2 billion in profit between 2018 and 2023 while employing 37 people.
Shell says those employees were skilled commodity traders genuinely responsible for substantial commercial risk.
That may be so.
They must certainly have been busy.
Thirty-seven people generating billions of dollars in profit makes the average British productivity debate look embarrassingly unambitious.
Perhaps the Dutch government should stop worrying about economic growth and simply relocate Rotterdam to Nassau.
Shell rejects allegations that it improperly shifted profits and says its transfer-pricing arrangements comply with OECD guidelines and applicable law.
That defence belongs in any serious account.
Unfortunately for satire, it also gives us the perfect institutional arrangement:
Shell says the tax authorities knew.
The tax authorities cannot say whether Shell is right.
Everybody wins.
Except perhaps Parliament, which would quite like an answer.
Dutch service companies discover socialism
Then there is the intriguing question of Shell service companies in the Netherlands.
According to the Shell Files investigation, some historic arrangements involved group services being recharged at cost without a profit mark-up.
Professor Jan van de Streek has publicly criticised aspects of those arrangements and reportedly considers some of them inconsistent with the arm’s-length principle.
Shell strongly disputes allegations of illegality.
The Dutch government has now helpfully explained the general rule without saying anything about Shell specifically.
Routine intra-group services generally attract an arm’s-length profit margin.
Certain qualifying low-value services can use a simplified 5% mark-up.
There can also be circumstances where no mark-up is justified.
And was Shell’s particular treatment correct?
Ah.
Article 67.
Fiscal confidentiality.
Next question.
For an oil company usually regarded as an enthusiastic practitioner of capitalism, the concept of one Shell company performing services for another without making a profit has a certain charming collectivist quality.
From each subsidiary according to its functions.
To each offshore entity according to its transfer-pricing documentation.
Karl Marx would presumably have asked to see the comparables.
Fortunately, Shell has experience with awkward numbers
Whenever Shell and complex financial numbers appear in the same story, students of corporate history may experience an involuntary flashback.
The year was 2004.
The subject was not tax.
It was something even more fundamental for an oil company:
oil and gas reserves.
Shell had repeatedly reported quantities of “proved” reserves to investors which did not satisfy the required SEC standards.
The ultimate scale was enormous.
The US Securities and Exchange Commission found that Shell had overstated its reported proved hydrocarbon reserves for 2002 by:
4.47 billion barrels of oil equivalent
or approximately:
23%
The SEC also found that the corresponding standardised measure of future cash flows was overstated by approximately $6.6 billion.
Shell paid a $120 million civil penalty in the US settlement.
The companies settled without admitting or denying the SEC’s substantive findings. SEC
That was not an activist allegation.
It was an enforcement action by the United States Securities and Exchange Commission.
And there is a particularly uncomfortable passage in the SEC record.
The Commission said the overstatement and delay in correcting it resulted partly from a desire to create and maintain the appearance of a strong reserves replacement ratio, an important performance measure watched by investors. SEC
In other words, Shell once had a problem involving numbers that looked excellent until someone examined how they had been classified.
Purely by coincidence, the present tax controversy involves arguments over where profits should be classified.
History does not repeat itself.
It sometimes does, however, develop an unfortunate sense of humour.
The important difference
There is a crucial distinction.
The reserves scandal produced regulatory findings.
The current transfer-pricing controversy has not.
No court judgment identified in the present material establishes that Shell’s leaked transfer-pricing arrangements were unlawful.
No Dutch government finding currently establishes that Shell received improper tax treatment.
No European Commission ruling identified here concludes that the arrangements constituted prohibited state aid.
SOMO, Follow the Money and tax academics have raised serious questions.
Shell disputes accusations of wrongdoing.
And the Dutch government will not disclose Shell’s individual tax treatment.
That distinction is not a minor legal footnote.
It is the difference between documented regulatory wrongdoing in 2004 and contested allegations in 2026.
Satire works better when the facts beneath it are accurate.
Shell has heard this tax tune before
What the older archive demonstrates is that the 2026 controversy did not appear from nowhere.
In 2009 the Guardian reported on Shell trademarks being held in Switzerland and royalty payments flowing there.
Shell denied that tax avoidance motivated the move and described the rationale as commercial. The Guardian
Years later, Shell’s Swiss intellectual-property arrangements have again become the subject of transfer-pricing scrutiny.
The old archive also records controversies involving Bermuda, Luxembourg and other offshore arrangements.
Again, the existence of an offshore company does not prove tax evasion.
Nor is tax avoidance necessarily unlawful.
Multinational groups operate across borders and legitimately organise financing, intellectual property and trading through international subsidiaries.
The interesting question is not whether Shell has subsidiaries in exotic locations.
It is whether the allocation of profit between them reflects genuine economic activity and complies with the arm’s-length principle.
That is precisely what the leaked documents have reopened for debate.
A short course in modern corporate transparency
The 2026 system can therefore be summarised as follows.
Shell publishes tax principles.
Shell says it complies with OECD rules.
Shell says relevant arrangements were discussed transparently with tax authorities.
Internal Shell documents leak.
Researchers analyse them.
Academics question them.
Parliament asks the Dutch government whether the tax authority agreed with Shell.
The government replies that taxpayer confidentiality prevents it from answering.
The government then assures Parliament that it sees no reason for a special investigation.
This is not secrecy in the traditional sense.
Traditional secrecy involves preventing people from learning something.
This is a more sophisticated Dutch model in which everybody knows what they are discussing, but the institution with the answer is legally prohibited from joining the conversation.
Sir Henri Deterding was right.
It really is an art form.
Imagine the reserves scandal under the same rules
For purposes of satire, imagine applying the current model retrospectively to 2004.
Investor: “Did Shell overstate its reserves?”
Shell: “We comply with all applicable reporting standards.”
Regulator: “We cannot discuss the affairs of an individual oil company.”
Investor: “But Shell just cut the reserves.”
Regulator: “We cannot confirm that the barrels you can no longer see were previously there.”
Investor: “The company announced it.”
Regulator: “Information becoming public does not remove our duty of confidentiality.”
Investor: “How many barrels are missing?”
Regulator: “Approximately—”
lawyer whispers
Regulator: “We cannot comment.”
Fortunately, securities regulation did not work that way.
The SEC investigated.
It published detailed findings.
Investors learned that the 2002 reserve overstatement amounted to approximately 23%.
Accountability became possible because the regulator could actually explain what it had found.
Tax confidentiality presents a different problem
Tax information is legitimately subject to greater confidentiality.
Nobody should pretend otherwise.
A functioning tax system depends upon businesses and individuals being able to provide sensitive information to revenue authorities.
The State Secretary therefore has a serious legal basis for refusing to disclose taxpayer-specific material.
But that does not eliminate the accountability problem exposed by the Shell Files.
Indeed, it creates it.
The public can inspect leaked material.
Parliament can ask questions.
Shell can provide its explanation.
Researchers can publish competing calculations.
But there is no public access to the most important piece of the puzzle:
what the Dutch tax authority actually concluded.
Perhaps it thoroughly examined the arrangements and found them correct.
Perhaps it challenged them.
Perhaps Shell made adjustments.
Perhaps rulings were reached.
Perhaps additional tax was paid.
Perhaps none of those things happened.
We do not know.
And the government says it cannot tell us.
Shell therefore occupies a remarkably comfortable position
The company can legitimately say:
“We discussed these matters with the tax authorities.”
Critics can ask:
“And did the tax authorities agree?”
The government responds:
“Confidential.”
Shell need not invoke secrecy itself.
The state does it for them.
This does not make Shell guilty of anything.
It does make independent verification rather difficult.
Which is rather convenient when your corporate history already contains a 2004 reminder that independent verification can occasionally uncover several billion barrels’ worth of unpleasant surprises.
The ghost of Sir Henri returns
Our fictional Deterding therefore wishes to amend yesterday’s statement.
“I initially praised the Dutch Ministry for turning tax secrecy into an art form. Having now reviewed the historical archive, I withdraw the compliment.
“This is no longer art.
“It is heritage.”
He would perhaps also observe that international tax planning has become unnecessarily complicated.
In his era, businesses went abroad because that was where the oil was.
Now apparently the oil can be in Nigeria, Brazil or the North Sea, the traders can be in the Bahamas, the trademarks can be in Switzerland, the parent company can move from The Hague to London, and the tax explanation can reside safely inside a Dutch government filing cabinet marked:
CANNOT COMMENT
Progress.
The serious conclusion behind the joke
There is a serious point beneath all of this.
Shell is one of the world’s largest multinational corporations.
It operates through hundreds of companies, across numerous tax systems, with internal transactions involving oil, gas, LNG, intellectual property, finance, technical services and commodity trading.
Transfer pricing is unavoidable.
The question is whether the rules consistently allocate taxable profit to the places where genuine economic value is created.
The Shell Files argue that the international system can produce outcomes in which very large profits appear in low-tax jurisdictions.
Shell says its arrangements reflect genuine commercial functions and comply with the rules.
Those competing positions deserve scrutiny.
The problem is that the Dutch institution best placed to resolve at least part of the argument is legally prevented from telling the public what it knows.
That may be entirely proper under current law.
But nobody should confuse legally mandated silence with exoneration.
The Dutch government has not cleared Shell of the allegations contained in the leaked transfer-pricing material.
It has declined to discuss Shell’s individual tax affairs.
Those are very different things.
And Shell’s history gives investors one further reason to insist upon precision.
In 2004, Shell’s proved-reserves numbers turned out to be overstated by 4.47 billion barrels — approximately 23%.
That episode taught a rather expensive lesson:
When dealing with a multinational oil company, the location and classification of billions can matter.
Then it was barrels.
Today it is profits.
And this time, the government says the answer is confidential.
Documentary sources
The current Shell tax controversy and Dutch government’s fiscal-confidentiality position are covered in today’s related articles:
Dutch Government Refuses to Reveal What It Knows About Shell Tax Leaks — Citing Tax Secrecy
Dutch Ministry of Finance Says Leaked Shell Tax Documents Remain Confidential: Cannot Confirm What Everyone Has Already Read
Shell Founder Hails Dutch Ministry’s Tax Secrecy as “An Art Form”
Read Sir Henri Deterding’s entirely fictional contribution
The site’s historical tax archive demonstrates that scrutiny of Shell’s international tax structures considerably predates the 2026 Shell Files:
Royal Dutch Shell Tax Avoidance Index
The Guardian’s 2009 investigation documented the transfer of Shell trademark ownership to Switzerland and Shell’s explanation that the move was made for commercial reasons. The Guardian
The US Securities and Exchange Commission’s 2004 enforcement record documents the 4.47-billion-barrel, approximately 23% proved-reserves overstatement and the $120 million civil penalty. SEC
Satirical disclaimer: Sir Henri Deterding died in 1939 and has not commented on Dutch tax policy, transfer pricing, the Bahamas, DEMPE functions or anything else since. Any purported remarks from him in this article are obviously fictional. The factual material surrounding the satire is drawn from the sources identified above.
Site-wide disclaimer applies.
*This website and sisters royaldutchshellgroup.com, shellnazihistory.com, royaldutchshell.website, johndonovan.website, shellnews.net, and shellwikipedia.com, are owned by John Donovan - more information here. There is also a Wikipedia segment, the Shell DPA Files, "Shell and the Spies", the Shell Leaks files, as well as books written and published by John Donovan - Kindle eBooks. Timeline of the Donovan Shell Feud. Toxic History of Royal Dutch Shell Group. Shell and the Donovans: The Full Media Record — 550+ Articles, 110 Books, 40 Years. *All created and supported by internet wizz, Nick Gill.