By the Donovan–Shell Archive | 16 November 2026
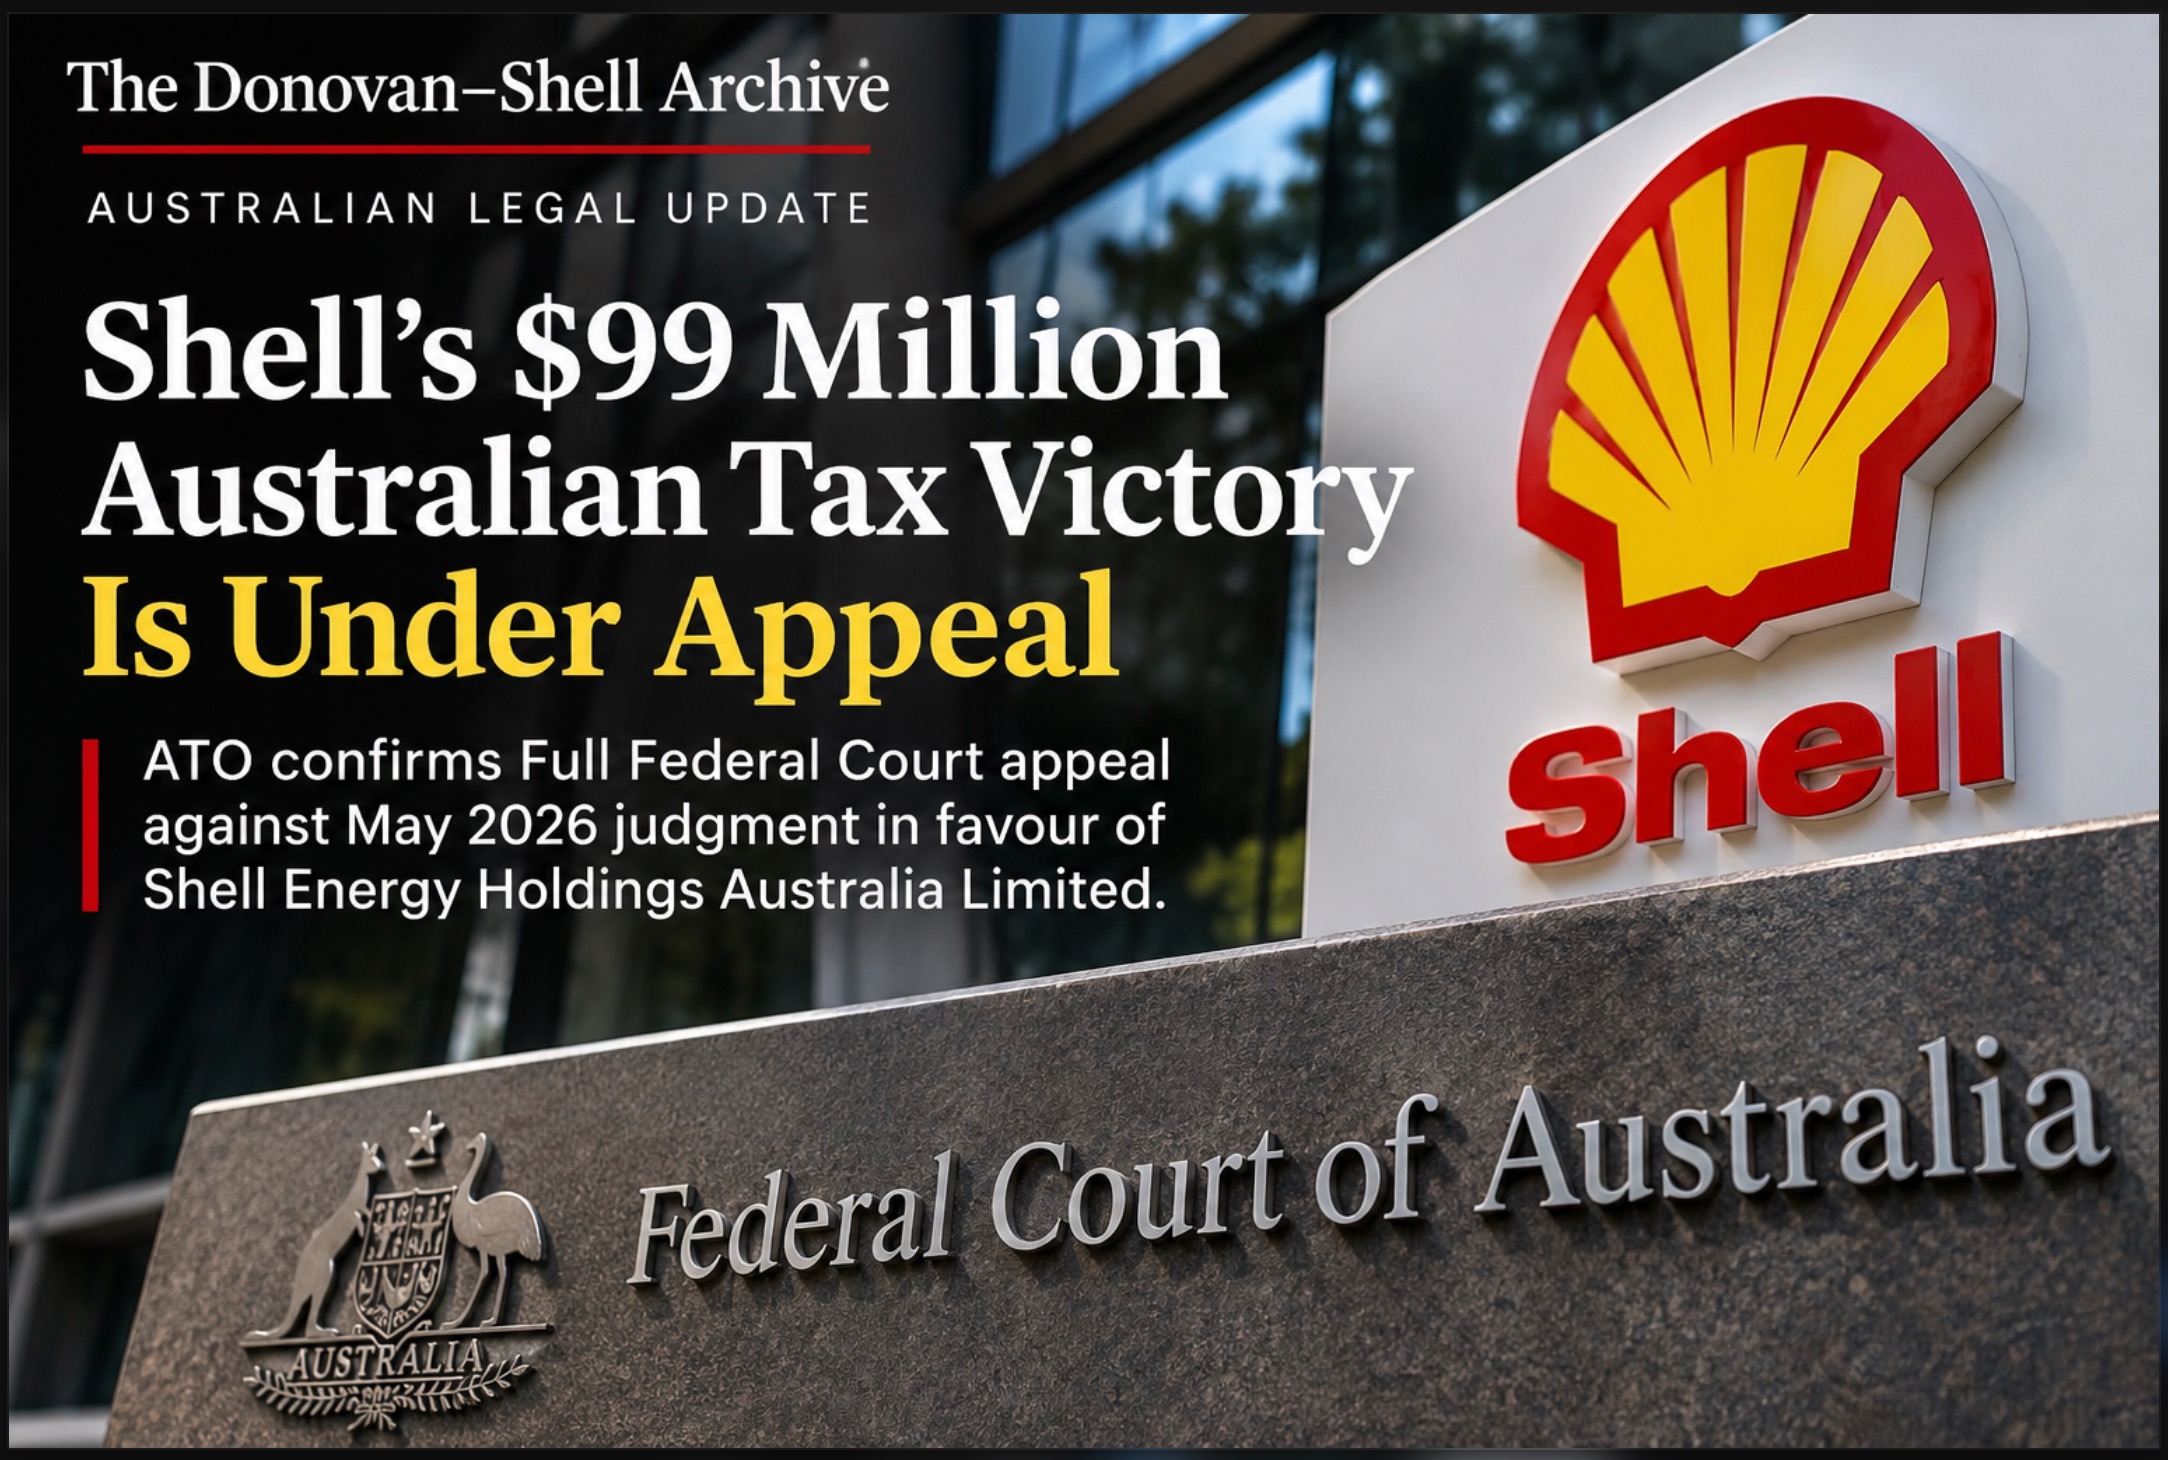
The Australian Taxation Office has confirmed that its dispute with Shell Energy Holdings Australia Limited over the valuation of a historic Woodside shareholding is before the Full Federal Court, despite Shell’s earlier victory in May 2026.
Shell’s substantial legal victory in an Australian capital gains tax dispute is not necessarily the final word.
An official Australian Taxation Office (ATO) report identifies Shell Energy Holdings Australia Limited v Commissioner of Taxation [2026] FCA 577 as an outcome unfavourable to the Commissioner and confirms that the matter is currently on appeal before the Full Federal Court.
The information is significant because the Federal Court’s original decision, delivered on 11 May 2026, overturned amended tax assessments arising from Shell’s historical investment in Woodside Petroleum Limited.
The dispute concerned approximately A$98.9 million in additional income tax assessed by the Commissioner.
What the original judgment established
The litigation arose from the treatment of Shell’s former 34.27% holding in Woodside Petroleum.
The central question was how to establish the market value of that substantial shareholding as at 20 January 1997, a date relevant to transitional Australian capital gains tax legislation.
The ATO argued for a valuation based essentially on the market price of individual Woodside shares.
Shell contended that the valuation should reflect the substantial influence attached to a holding representing more than one-third of Woodside’s issued shares.
Justice Ian Jackman accepted Shell’s position.
His judgment determined a value of A$11.12 per share, incorporating an 18% premium over the closing market price of A$9.42.
The Court set aside the Commissioner’s objection decision, finding that Shell had established that the amended assessments were excessive.
This was a judicial finding in Shell’s favour, not merely an assertion by the company.
Shell also won its costs dispute
The favourable judgment was followed by a further decision on 7 July 2026.
In Shell Energy Holdings Australia Limited v Commissioner of Taxation (Costs) [2026] FCA 882, Justice Jackman ordered the Commissioner to pay Shell’s costs on the ordinary party-and-party basis up to the specified February 2026 date and on an indemnity basis thereafter.
The ruling followed Shell’s earlier offer to compromise the dispute, which the Commissioner had rejected.
The costs judgment represented an additional procedural and financial victory for Shell.
The ATO confirms the litigation continues
The ATO’s official findings report now provides an important qualification to the apparent finality of those victories.
It identifies the May 2026 judgment as being under appeal before the Full Federal Court.
That confirmation means the first-instance outcome remains subject to appellate review.
However, the precise grounds of appeal, the appellate proceeding number and the hearing timetable have not yet been independently established from publicly accessible court records reviewed for this report.
The ATO’s report was last updated on 17 September 2026. Its appearance in the present investigation should therefore not be mistaken for evidence that an appeal was commenced in November.
Nor should the existence of an appeal be interpreted as establishing that the Commissioner will succeed or that Shell’s earlier victory has been overturned.
Why this case matters
The case illustrates how disputes involving historical corporate shareholdings can produce substantial tax consequences decades after the original investments.
It also raises legal questions about how the value of a significant corporate shareholding should be determined under transitional tax legislation.
The May judgment accepted that a large shareholding could command a premium reflecting its capacity to confer significant influence, rather than being valued simply as individual shares traded on the stock exchange.
The Full Federal Court proceedings may therefore be important in determining whether that interpretation survives appellate scrutiny.
There is an important limitation: the relevant legislation concerned historical transitional provisions, and the extent of any wider precedent will depend on the appellate issues and eventual decision.
What remains unresolved
Three questions require further documentary verification.
First, precisely which findings or conclusions from Justice Jackman’s judgment are being challenged?
Second, when will the Full Federal Court hear the appeal?
Third, will the original judgment and associated costs orders ultimately remain undisturbed?
Until those questions can be answered, the appropriate conclusion is that Shell won the first round of this substantial tax dispute, but the appellate process is not yet resolved.
This is a tax valuation dispute involving Shell Energy Holdings Australia Limited as a direct party. It does not involve a judicial allegation or finding of tax fraud.
The Donovan–Shell Archive will continue examining the available Australian court records and official ATO disclosures for material developments.
Principal sources
- Australian Taxation Office — Public and multinational business disputes and outcomes
- Shell Energy Holdings Australia Limited v Commissioner of Taxation, [2026] FCA 577 — judgment summary
- Shell Energy Holdings Australia Limited v Commissioner of Taxation (Costs), [2026] FCA 882 — judgment summary
- PwC Australia — June 2026 Tax Update
Editorial note: This report draws on the Australian Taxation Office’s official litigation summary, published judgments as described in legal reporting, and independent tax-law commentary. The appellate status is confirmed by the ATO; the appeal documents themselves have not yet been independently examined. AI-assisted research and drafting were subject to documentary cross-checking.
The draft is supported by the ATO’s explicit appeal-status statement, the reported May valuation findings and the July costs decision.
Australian Taxation Office+3